
The government can boost its tax revenue by strengthening and expanding the country’s economic activities. Achieving this requires improving the ease of doing business.
The government has announced plans to streamline various taxes, levies, and CESS by consolidating them into a single tax system, thereby making it easier to conduct business.
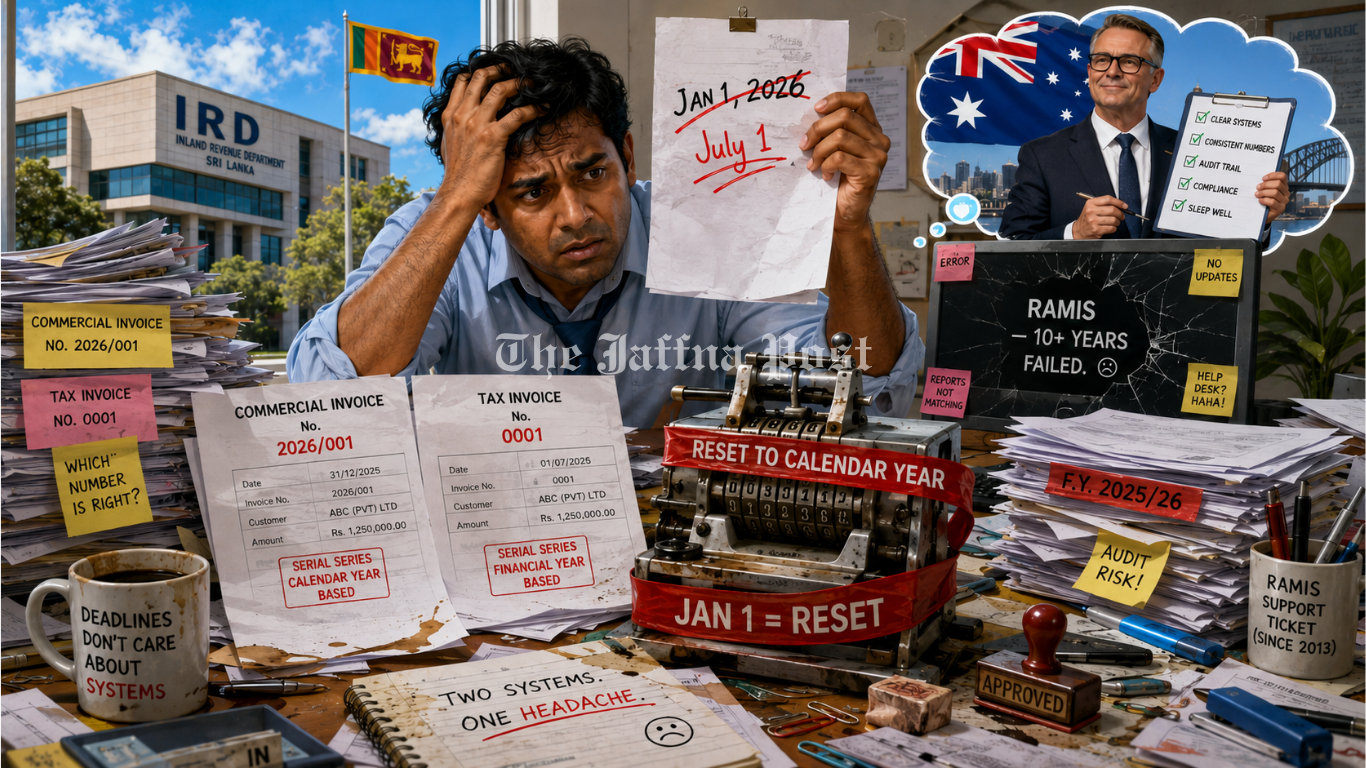
The Inland Revenue Department (IRD) has now issued regulations for VAT procedures through a gazette notification dated November 17, 2025, initially set to take effect from January 1, 2026. It has now been postponed to July 1, with some sensible improvements.
Commercial Invoice vs. Tax Invoice
However, It remains unclear whether separate Tax Invoice No. conforming to the given format different from the regular commercial invoice No. issued by an organization is to be assigned, or a standard commercial invoice No modified to conform to the given format
So far, most organizations have been using a modified commercial invoice labeled as a Tax invoice number.
When processing supplier invoices, both the commercial invoice number and the tax invoice number must be captured and provided to the purchaser, particularly when the purchaser is VAT-registered.
The tax invoice number given by supplier must also be reported in input tax returns.
This introduces additional administrative workload, especially for organizations with manual processes. Even for computerized systems, these changes increase operational complexity and cost.
Commercial Invoice Modification
If the prescribed format applies to the commercial invoice No., it may require maintaining two serial numbers, one for non-VAT registered and another one for VAT registered which organizations generally prefer to avoid.
Ideally, organizations would use a single, continuous serial number for all invoices, both tax and non-tax, regardless of the issuing branch. This would improve system consistency and reliability.
However, even where a single branch or a common Serial Number is used, the format may require introducing a redundant branch code.
Normally commercial organizations require rest of Invoice serial Number at the end of the financial year. However, the IRD expects serial No reset at the end of the calendar year.
Additionally, if a customer initially receives a non-tax invoice but later requests a tax invoice, the organization must issue another one, resulting in two invoices for the same transaction.
This will involve the IRD getting into and changing internal processes and controls.
Detecting Leaks
These requirements are intended to prevent revenue leakages by enabling validation of input tax credits claimed by one taxpayer against the corresponding output reported by the supplier using the Invoice Number.
However, enforcing invoice-by-invoice matching presents practical challenges, particularly because invoice number formats may not align exactly between the supplier’s output schedules and the purchaser’s input schedules.
To address this, the IRD has imposed a standardized invoice format—effectively shifting the burden of resolving matching issues onto businesses rather than developing an internal solution. I am at a loss why formats of invoice Numbers be identical for invoices to be matched.
In practice, a significant degree of matching could be achieved by comparing the number of transactions and total values of given pair of suppliers and purchasers for each day. In most cases, there is likely to be only one transaction per day between two parties, except for pairs of large organizations with multiple daily transactions.
This process will remove all difficulties of invoice matching by invoice Numbers reported by customer supplier pair. Instead, it will be by the invoice date.
Instead of designing a system that accommodates real-world business practices, the IRD appears to be forcing businesses to adapt to an inefficient system, thereby reducing overall national productivity.
Instead of fixing RAMIS, the tax administration system, which reportedly consumed billions of rupees yet remains problematic, business enterprises are burdened with procedures designed by people who have no overall systems perspective.
One could observe repeat performance of the introduction of Tax Identification Numbers (TIN) for all individuals above 18 years without using the National Identity Numbers, reflecting poor system design.
Even a ministerial subcommittee of the previous government acknowledged that RAMIS had been ineffective for over a decade and recommended appointing a new vendor. However, there has been little visible progress on this matter over the past year.
Example of Other Countries
In Australia, there is no requirement to upload individual tax invoices for compliance purposes. Instead, the system relies on alternative mechanisms to ensure accuracy and adherence to tax regulations.
The responsibility largely rests with financial auditors to verify that companies submit proper and complete tax returns. If the tax authorities subsequently uncover non-compliance after audited financial statements have been filed, significant penalties can be imposed on the auditors, as they are legally obligated to ensure that all compliance requirements have been properly met.
Conclusion: Is the government trying to make doing business in Sri Lanka difficult?